insurance claim evidence chronology: key takeaways
A claim-support chronology is useful when each timestamp has a defined event, source, owner, and unresolved dependency.
- Define the claim event and timestamp meaning.
- Preserve source and receipt dates independently.
- Trace handoffs and waiting dependencies.
- Escalate coverage and adjustment decisions.
Research plan dated 2026-08-21
This review tests whether official sources provide a defensible benchmark for insurance claim evidence chronology. It keeps reported figures separate from local operating measures.
- Sample claim-support records across channels and event types.
- Map source creation, agency receipt, routing, response, and closure timestamps.
- Classify missing, duplicate, inferred, and verified events.
- Test whether the chronology supports a safe escalation without implying claim authority.
insurance claim evidence chronology: what the current data says
A claim record often contains several dates for one event. Treating them as one timestamp can hide where a delay or uncertainty actually occurred.
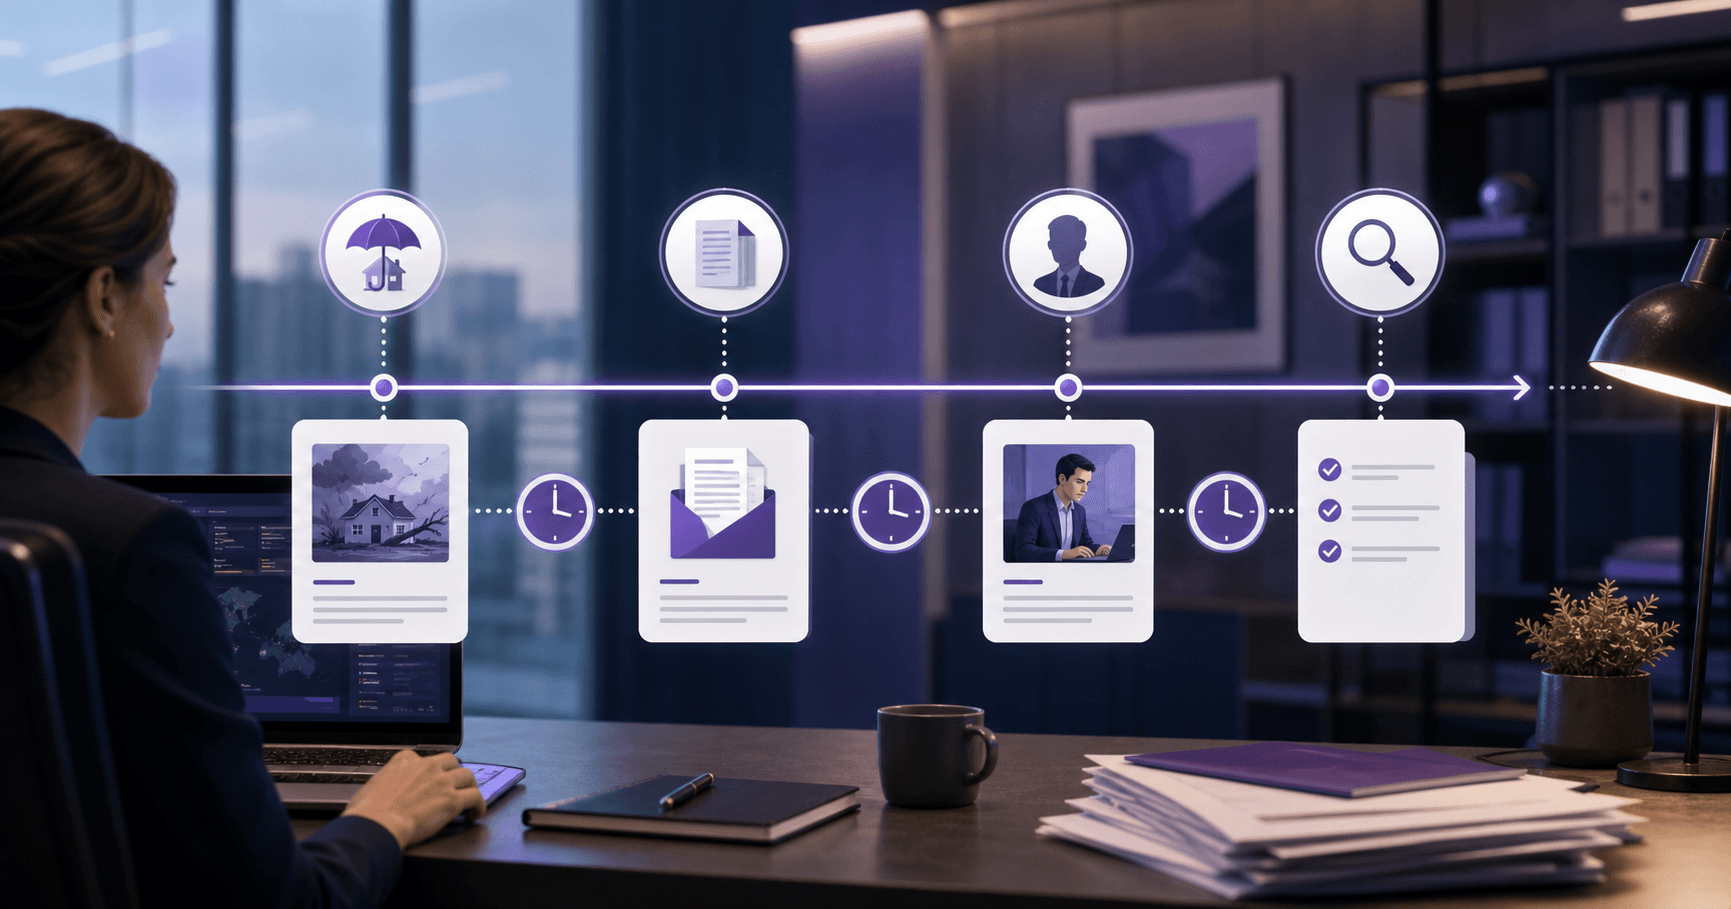
Research question. Can an agency show what happened between a reported loss, receipt of evidence, carrier handoff, follow-up, and closure without turning a chronology into a claim decision? A claim-support file may contain a reported loss date, message timestamp, staff receipt time, entry time, carrier acknowledgment, request for documents, response, and status update. Each date answers a different question. Collapsing them loses the route of the work.
Define the event before recording its date. ‘Notice received’ should identify the channel and recipient. ‘Sent to carrier’ should identify the transmission and destination. ‘Carrier acknowledged’ should require a source response rather than a staff assumption. ‘Follow-up completed’ should state what was checked and what remains open. A timestamp without an event definition can be precise while being operationally meaningless.
Keep source creation and agency receipt separate. A client may send a message after a loss but before the agency sees it. A portal may show upload time while the downloaded document is indexed later. A phone note may record when a call began but not when a requested attachment arrived. The chronology should preserve the source and the local handling event rather than choosing the most convenient date.
Create a chronology with at least event, source, timestamp, time zone, owner, channel, affected claim or policy, dependency, and evidence link. Mark inferred times explicitly. If a carrier acknowledgment is absent, record no acknowledgment found rather than assuming delivery failed or succeeded. If a document appears to have been sent twice, preserve both attempts and the reason for the second one.
Sample routine and difficult notices. Include email, phone, portal, mail, vendor communication, weather-related urgency, late reports, duplicate reports, and notices with an unclear policy reference. The purpose is not to judge the claim. It is to see whether the administrative record preserves enough context for a licensed or carrier owner to decide what must happen next.
Study handoffs rather than merely elapsed time. Record when an agency worker received a report, when it was assigned, when information was requested, when a carrier or adjuster became responsible, and when the next response was verified. A long interval may be an external dependency. A short interval may still be unsafe if the wrong policy or incomplete source was forwarded. Chronology should expose both possibilities.
Compare the original message, internal record, transmitted packet, acknowledgment, and follow-up note. Look for changed loss descriptions, dropped qualifiers, missing attachments, duplicate claim references, and status language that exceeds the source. Corrections should be additive where possible. The later accurate note should not make the earlier ambiguity disappear from the research sample.
External sources provide only bounded context. NAIC market-conduct materials can inform regulatory record questions, while ACORD can inform structured exchange. BLS describes clerical occupation context and CISA offers general control guidance. None supports an agency claim-handling speed, claim severity, liability conclusion, or coverage interpretation. Those matters belong to the carrier, adjuster, producer, or other authorized professional under the applicable arrangement.
Measure the chronology with event-level denominators. Useful observations include the share with independent source and receipt times, verified handoff, documented dependency, acknowledgment, next-owner assignment, and closure evidence. Track duplicate work, missing-source exceptions, inferred timestamps, and reopened items. Do not summarize these figures as a claims outcome, customer satisfaction result, or regulatory compliance rate without a separate validated study.
Use a reconstruction exercise. Give a second reviewer the source messages, attachments, chronology, handoff evidence, and notes. Ask what was reported, when the agency received it, what was sent, who owns the next decision, and what remains unverified. Record where the reviewer must infer. A successful reconstruction means the evidence supports a handoff; it does not mean the claim is covered or properly adjusted.
Limitations include time-zone ambiguity, phone-only reports, delayed carrier acknowledgments, inaccessible portals, privacy limits, catastrophe volume, and records created after the fact. A chronology cannot prove the truth of a loss description, the cause of damage, liability, or a settlement value. It can show whether the agency preserved the administrative sequence and signaled uncertainty rather than inventing certainty.
Chronology research should also preserve negative evidence. If no acknowledgment was found, no document was available, or a callback did not establish the requested fact, that absence belongs in the event sequence with the search boundary. Negative evidence is not proof that an event never occurred; it is a truthful statement about what the reviewed records support. Record the systems, channels, and cutoff searched, then assign an owner for any consequential gap. This gives the next reviewer a proportionate starting point and prevents a missing artifact from being silently converted into either a failure or a successful handoff.
The study should report chronology quality by event type. A sample may preserve receipt time well while lacking carrier acknowledgment or closure evidence. Combining those fields into one pass measure hides the exact control that needs attention. Separate reporting also helps an authorized owner choose a proportionate remedy, such as a channel confirmation rule, a handoff template, or a documented escalation path.
Evidence-led conclusion. Claim-support chronology is defensible when source time, receipt time, handoff time, acknowledgment, dependency, and closure are distinct and linked to evidence. The record supports disciplined routing and follow-up, not a coverage or adjustment conclusion. InsuranceYo can research that operational evidence chain while keeping claim authority and interpretation with the properly authorized parties. The measured conclusion remains deliberately narrow.
A safe role design separates advice and authority from documented administration. Support staff can collect records, update systems, prepare work, and maintain follow-ups under written procedures. Licensed staff remain responsible for coverage discussions, recommendations, approvals, and any activity restricted by law or carrier agreement.
Consolidated statistics
Screenshot-ready table. Verified August 21, 2026. These figures are benchmarks and context, not an observed industry average or a modeled scenario.
| Source | Metric | Published value | Geography and population | Date | Caveat |
|---|---|---|---|---|---|
| NAIC Market Conduct Annual Statement | Regulatory context | Market-conduct reporting framework | United States insurance regulation | Reference checked August 21, 2026 | A reporting framework is not an agency performance benchmark. |
| ACORD Property and Casualty Data Standards | Data exchange context | P&C data standards documentation | Insurance data exchange | Reference checked August 21, 2026 | A standard does not prove that a local record is complete or correct. |
| BLS Occupational Outlook Handbook, Financial Clerks | Occupation context | Insurance claims and policy processing clerks | United States labor market | 2024 employment and May 2024 wage data | Occupation data does not measure an agency's queue, quality, or staffing need. |
| CISA Cybersecurity Performance Goals | Control context | Identity, access, and response practices | United States guidance | Reference checked August 21, 2026 | Guidance is not proof that an agency has implemented a control. |
Workflow and controls
| Stage | Control |
|---|---|
| 1 | Define the claim event and timestamp meaning. |
| 2 | Preserve source and receipt dates independently. |
| 3 | Trace handoffs and waiting dependencies. |
| 4 | Escalate coverage and adjustment decisions. |
Sources and method
Methodology (verified August 21, 2026; 2026-08-21): one observation is a claim-support event with event definition, source, source timestamp, agency receipt timestamp, owner, handoff, dependency, and disposition. External context includes NAIC Market Conduct Annual Statement (https://content.naic.org/insurance-topics/market-conduct-annual-statement), ACORD Property and Casualty Data Standards (https://www-dev.acord.org/standards-architecture/acord-data-standards/Property_Casualty_Data_Standards), BLS Financial Clerks data (https://www.bls.gov/ooh/office-and-administrative-support/financial-clerks.htm), and CISA Cybersecurity Performance Goals (https://www.cisa.gov/cybersecurity-performance-goals). None determines coverage, liability, adjustment, or settlement.
- NAIC Market Conduct Annual Statement, Reference checked August 21, 2026.
- ACORD Property and Casualty Data Standards, Reference checked August 21, 2026.
- BLS Occupational Outlook Handbook, Financial Clerks, 2024 employment and May 2024 wage data.
- CISA Cybersecurity Performance Goals, Reference checked August 21, 2026.
Frequently asked questions
What does this study establish?
It establishes a chronology research method, not claim liability, coverage, settlement value, or adjustment advice.
Do national labor figures predict one agency's cost?
No. They are benchmarks. Location, role mix, benefits, tools, management, and workload determine actual cost.
Which work should stay with licensed staff?
Coverage advice, recommendations, binding authority, and regulated activity should remain with properly licensed and authorized staff.
Want to map this workload in your agency?
InsuranceYo can help separate licensed decisions from documented support work and outline a practical staffing plan.
Talk through your workflow